EPF withdrawal rules changed in a big way in 2026. The Employees’ Provident Fund Organisation (EPFO) cut 13 complicated withdrawal reasons down to three, raised how much you can take out, and changed the waiting time after you lose your job. Here is how the new system works and how to claim online.
Quick answer
Under the EPF Scheme, 2026 (notified under the Code on Social Security, 2020, effective 29 June 2026), partial EPF withdrawal falls into three categories: essential needs (illness, education, marriage), housing, and special circumstances. You can take up to 100% of the eligible balance, but must keep at least 25% in the account, after at least 12 months of membership.
After job loss, you can withdraw 75% at once and the remaining 25% after 12 months without a job. Pension (EPS) can be withdrawn only after 36 months. Claims are filed online on the UAN member portal with Aadhaar OTP, and advance claims up to ₹5 lakh are settled automatically.
What changed in 2025–2026
| Point | Earlier | Now |
|---|---|---|
| Reasons for partial withdrawal | 13 separate purposes with different rules | 3 categories; no reason needed under “special circumstances” |
| Amount | Mostly employee share, with caps | Up to 100% of eligible balance (employee + employer share), keeping 25% minimum balance |
| Minimum service | Varied (up to 7 years) | 12 months for all partial withdrawals |
| Education / marriage | Up to 3 times in total | Education up to 10 times, marriage up to 5 times |
| Final PF settlement after job loss | After 2 months unemployed | 75% at once; balance after 12 months unemployed |
| Pension (EPS) withdrawal | After 2 months | After 36 months |
| Auto-settlement limit | ₹1 lakh | ₹5 lakh (from June 2025) |
These changes were approved by EPFO’s Central Board of Trustees in October 2025 and notified as the EPF Scheme, 2026. The aim is to let members meet needs while keeping retirement savings intact.
Before you apply for EPF withdrawal
- UAN activated and linked to Aadhaar.
- KYC complete: Aadhaar, PAN and bank account (with IFSC) verified in the member portal.
- Name, date of birth and gender match across Aadhaar, PAN and EPFO records. Mismatches are the commonest reason for rejection.
- Date of exit updated by the employer (or by you, two months after leaving) for final settlement.
- Previous accounts transferred to your current UAN, so the full service and balance count.
EPF withdrawal online: step by step
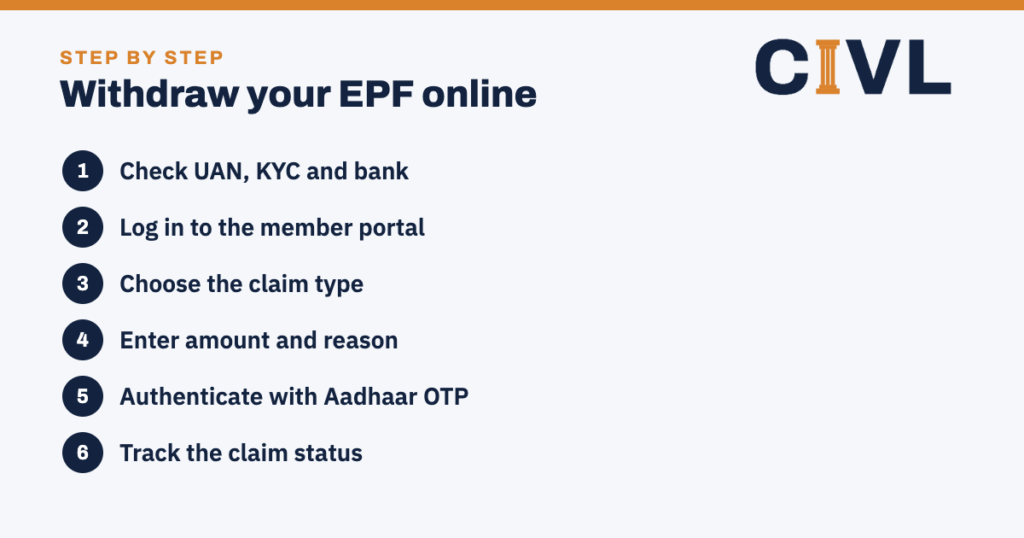
- Check UAN, KYC and bank details on the member portal.
- Log in to the EPFO member portal (unifiedportal-mem.epfindia.gov.in) or the UMANG app.
- Choose the claim type: partial withdrawal (advance), final PF settlement, or pension withdrawal.
- Enter the amount and category, and upload a cheque or passbook image if asked.
- Authenticate with Aadhaar OTP and submit.
- Track the claim under “Track claim status”. Advance claims up to ₹5 lakh are usually settled automatically within days.
EPFO has been testing withdrawal through UPI and ATMs (often called EPFO 3.0). As of November 2026 it has not launched for all members, so use the member portal or UMANG.
Tax on EPF withdrawal
- EPF withdrawal after 5 years of continuous service (including service with earlier employers, if transferred) is tax-free.
- If you withdraw before 5 years and the amount is ₹50,000 or more, EPFO deducts TDS at 10% (higher without PAN).
- TDS is not deducted if service ended because of ill health, closure of the employer’s business or other reasons beyond your control.
- If your total income is below the taxable limit, submit the self-declaration form so that TDS is not deducted.
Transfer instead of withdrawal
When you change jobs, transferring your PF to the new employer’s account keeps your service continuous for tax and pension purposes. Most transfers are now automatic once your UAN is linked; if not, file an online transfer request on the member portal.
If your EPF claim is rejected or delayed
- Read the rejection reason in “Track claim status”; most relate to KYC or bank mismatches.
- Correct details through the “Joint Declaration” or KYC update on the portal, with employer approval where needed.
- File a grievance on EPFiGMS (epfigms.gov.in) with the claim ID.
- If the employer does not cooperate, mention this in the grievance and approach the regional PF office.
EPF withdrawal for a house
Housing is one of the three categories under the new rules. You can use an EPF withdrawal to buy or build a house, buy a plot, or repay a home loan, subject to the 25% minimum balance. Keep the sale agreement, loan sanction letter or plan approval ready, as EPFO may ask for them. Read our sale deed registration guide before you buy.
EPF withdrawal for medical treatment
Illness of the member or a family member falls under “essential needs”. Medical advances are usually processed quickly and are among the claims eligible for automatic settlement. Keep the hospital estimate or bills with you in case they are asked for.
EPF withdrawal at retirement
At 58, you can withdraw the full PF balance, and the pension under the Employees’ Pension Scheme starts if you have at least 10 years of service. Before retiring, check that all past accounts are merged into your UAN so that the full service counts for pension.
If the member has died
The nominee or legal heirs claim the PF balance, pension and EDLI insurance together through the composite claim on the EPFO portal, with the member’s death certificate. If there is no nominee, the family may need a succession certificate or other proof of heirship.
EPF forms explained
Online claims now use one composite form behind the scenes, but the old form numbers still appear on the portal, in employer letters and in EPFO circulars. This is what each one is for:
| Form | Used for |
|---|---|
| Form 31 | Partial withdrawal (advance) from the PF account while you are still a member |
| Form 19 | Final settlement of the provident fund after leaving a job |
| Form 10C | Withdrawal of the pension (EPS) amount, or a scheme certificate to carry pension service forward |
| Form 10D | Monthly pension at age 58 (or reduced early pension from age 50) |
| Form 13 | Transfer of PF from an old employer’s account to the current one |
| Form 20 | PF settlement by the nominee or legal heir after a member’s death |
| Form 5(IF) | EDLI insurance claim by the family after a member’s death |
| Form 15G / 15H | Declaration to avoid TDS when your total income is below the taxable limit (15H is for senior citizens) |
EPF withdrawal offline
If you cannot claim online (for example, because KYC is incomplete or your Aadhaar details do not match), you can still apply on paper. Download the Composite Claim Form from the EPFO website. There are two versions:
- Composite Claim Form (Aadhaar): for members whose UAN is linked to Aadhaar and bank details are seeded. It can be sent to the EPFO regional office without the employer’s signature.
- Composite Claim Form (Non-Aadhaar): must be attested by the employer before it is submitted.
Attach a cancelled cheque or a copy of the bank passbook showing your name, account number and IFSC. Submit the form at the EPFO regional office that holds your account, keep the acknowledgement, and track the claim online with your UAN or the claim reference number. Offline claims usually take longer than online ones, so treat this as a fallback.
Check your EPF balance before you apply
Knowing your balance helps you choose the right amount and spot missing contributions before you file for EPF withdrawal. You can check it in four ways:
- EPFO passbook portal: log in with your UAN to see month-wise employee and employer contributions and the pension share.
- UMANG app: open the EPFO service and choose “View passbook”.
- Missed call: give a missed call to 9966044425 from the mobile number registered with your UAN.
- SMS: send “EPFOHO UAN ENG” to 7738299899 from the registered mobile (replace ENG with a language code for other languages).
If any month is missing, ask your employer to deposit the contribution before you apply. A claim is settled only on the amount actually credited to your account.
Should you withdraw, or keep your EPF?
EPF earns a tax-free interest rate set every year (8.25% for 2025–26), backed by the government, and it compounds for as long as the money stays in. That makes it one of the safest long-term savings options available to salaried people. Each early withdrawal reduces the corpus you will have at retirement.
A simple example: ₹2 lakh left in EPF for 20 years at about 8% grows to roughly ₹9 lakh. Withdrawn today, that future value is lost. So, before an EPF withdrawal, consider:
- Is the need real and urgent (medical treatment, a house, education), or can it wait?
- Could a lower-cost option work, such as an employer loan or a loan against a fixed deposit?
- If you are changing jobs, will a transfer to the new employer keep your service continuous and avoid tax?
- Would withdrawing before five years of continuous service attract tax and TDS?
This is general information, not financial advice. For large or tax-sensitive withdrawals, speak to a qualified tax adviser.
EPF withdrawal if you move abroad
Members who leave India to settle permanently abroad, or who take up a job in a country with which India has a Social Security Agreement, have different options. Under such agreements, an Indian worker posted abroad may continue in EPF and get a Certificate of Coverage instead of paying into the foreign system. If you are moving abroad for good, check the current EPFO rules on final settlement and keep proof of migration (such as a visa or overseas employment letter) ready.
Where to complain about an EPF claim
- First, check the rejection reason under “Track claim status” and fix it (KYC, bank details, date of exit).
- If the problem continues, file a grievance on the EPFO grievance portal (EPFiGMS) with your UAN and claim ID.
- You can also raise the issue through CPGRAMS, the central government public grievance portal.
- For employer defaults (contributions deducted but not deposited), the regional EPFO office can start recovery proceedings against the employer.
How long does EPF withdrawal take?
| Type of claim | Usual time |
|---|---|
| Advance claims under the auto-settlement limit | Often within 3 to 4 working days, without manual checks |
| Other advance and final settlement claims | Within about 20 days of a complete claim, the time set in the EPF Scheme |
| Claims with KYC or employer issues | Longer; the claim may be returned until the problem is fixed |
| Death claims (PF, EDLI and pension) | Depends on documents; EPFO treats them as priority claims |
Once the claim status shows “settled”, the money usually reaches the bank account in a few working days. If it does not, check that the bank account is still active and that the IFSC on record is current; bank mergers often change IFSC codes.
Documents to keep ready
- UAN and the mobile number linked to it (for OTPs)
- Aadhaar and PAN, with the same name and date of birth as in EPFO records
- Bank account in your own name, seeded in the portal, plus a cancelled cheque or passbook image
- For a house: sale agreement, allotment letter or loan documents if asked
- For medical treatment: details of the hospital and treatment, if the form asks for them
- For final settlement: date of exit from the last employer, and Form 15G or 15H if eligible
Keep copies of every claim you file and the settlement letter. They help if a dispute about your EPF withdrawal or service history comes up later, for example when you apply for a pension.
How withdrawal affects your pension
Your monthly contribution is split: the employee share and part of the employer share go to the provident fund (EPF), while 8.33% of wages (on wages up to ₹15,000) goes to the Employees’ Pension Scheme (EPS). A PF advance does not touch the pension account. But if you withdraw the EPS amount when you leave a job, your past pension service is wiped out, and you start again from zero in the next job.
Pension needs at least 10 years of service in total. So if you have, say, seven years of service and expect to keep working in jobs covered by EPFO, it is usually better to take a scheme certificate (or simply transfer to the new employer) instead of withdrawing the pension share. That way the seven years count towards the 10 needed for a lifelong monthly pension.
A full EPF withdrawal and a pension withdrawal are two separate choices on the claim form. Read the options carefully before you submit, because a pension withdrawal cannot be undone.
Common mistakes to avoid
- Withdrawing the whole PF on every job change and losing tax-free status and pension service.
- Trying to withdraw pension before 36 months under the new rules.
- Name or date-of-birth mismatches between Aadhaar and EPFO records.
- Entering a bank account that is not seeded with your name or is closed.
- Not transferring old accounts, so service appears shorter than it is.
Frequently asked questions
How much can I take out in a partial EPF withdrawal?
Up to 100% of the eligible balance (employee and employer share), but at least 25% must stay in the account.
What is the minimum service for EPF withdrawal?
12 months of membership for partial withdrawals under the 2026 rules.
Can I withdraw all my PF after losing my job?
You can withdraw 75% at once and the remaining 25% after 12 months of unemployment.
How long does EPF withdrawal take?
Auto-settled advance claims up to ₹5 lakh are usually paid within a few days. Other claims can take longer, depending on checks.
Is TDS deducted on EPF withdrawal?
Only if service is under 5 years and the amount is ₹50,000 or more, at 10% with PAN.
Can I withdraw EPF through UPI?
EPFO has been testing it, but as of November 2026 it is not available to all members.
Do I need my employer’s approval?
Not for most online claims if your KYC is complete and the date of exit is updated. Corrections to records may need employer approval.
Can I do EPF withdrawal without a reason?
Under the 2026 rules, the “special circumstances” category does not need a reason, subject to the 12-month service rule and the 25% minimum balance.
Will EPF withdrawal reduce my pension?
Withdrawing PF does not reduce pension if you leave the EPS balance untouched and keep your service continuous.
Where can I get a ready-to-use affidavit for name or date mismatches?
Use the CIVL name change affidavit format where your name differs across documents, along with the corrections process explained in our PAN card correction guide.
How many times can I do EPF withdrawal in a year?
There is no single yearly cap. Each category has its own limits, for example education up to 10 times and marriage up to 5 times over your membership, and you must keep the minimum balance.
Does EPF withdrawal need employer approval?
No, if your UAN is linked to Aadhaar and KYC is complete. The employer only needs to update your date of exit for a final settlement.
Is TDS deducted on EPF withdrawal?
TDS applies when you withdraw more than ₹50,000 before five years of continuous service. Submit Form 15G or 15H if your income is below the taxable limit, and give your PAN to avoid a higher TDS rate.
Can I withdraw the pension (EPS) amount?
Only in limited cases. With less than 10 years of service, you can withdraw the EPS amount (subject to the waiting period); after 10 years, you get a monthly pension instead.
CIVL format
Fix mismatched records
Name different across Aadhaar, PAN and EPFO? Use the name change affidavit format, and read our PAN card correction guide and Aadhaar update guide. For tax on rent, see the HRA exemption guide. Questions? Ask CIVL.